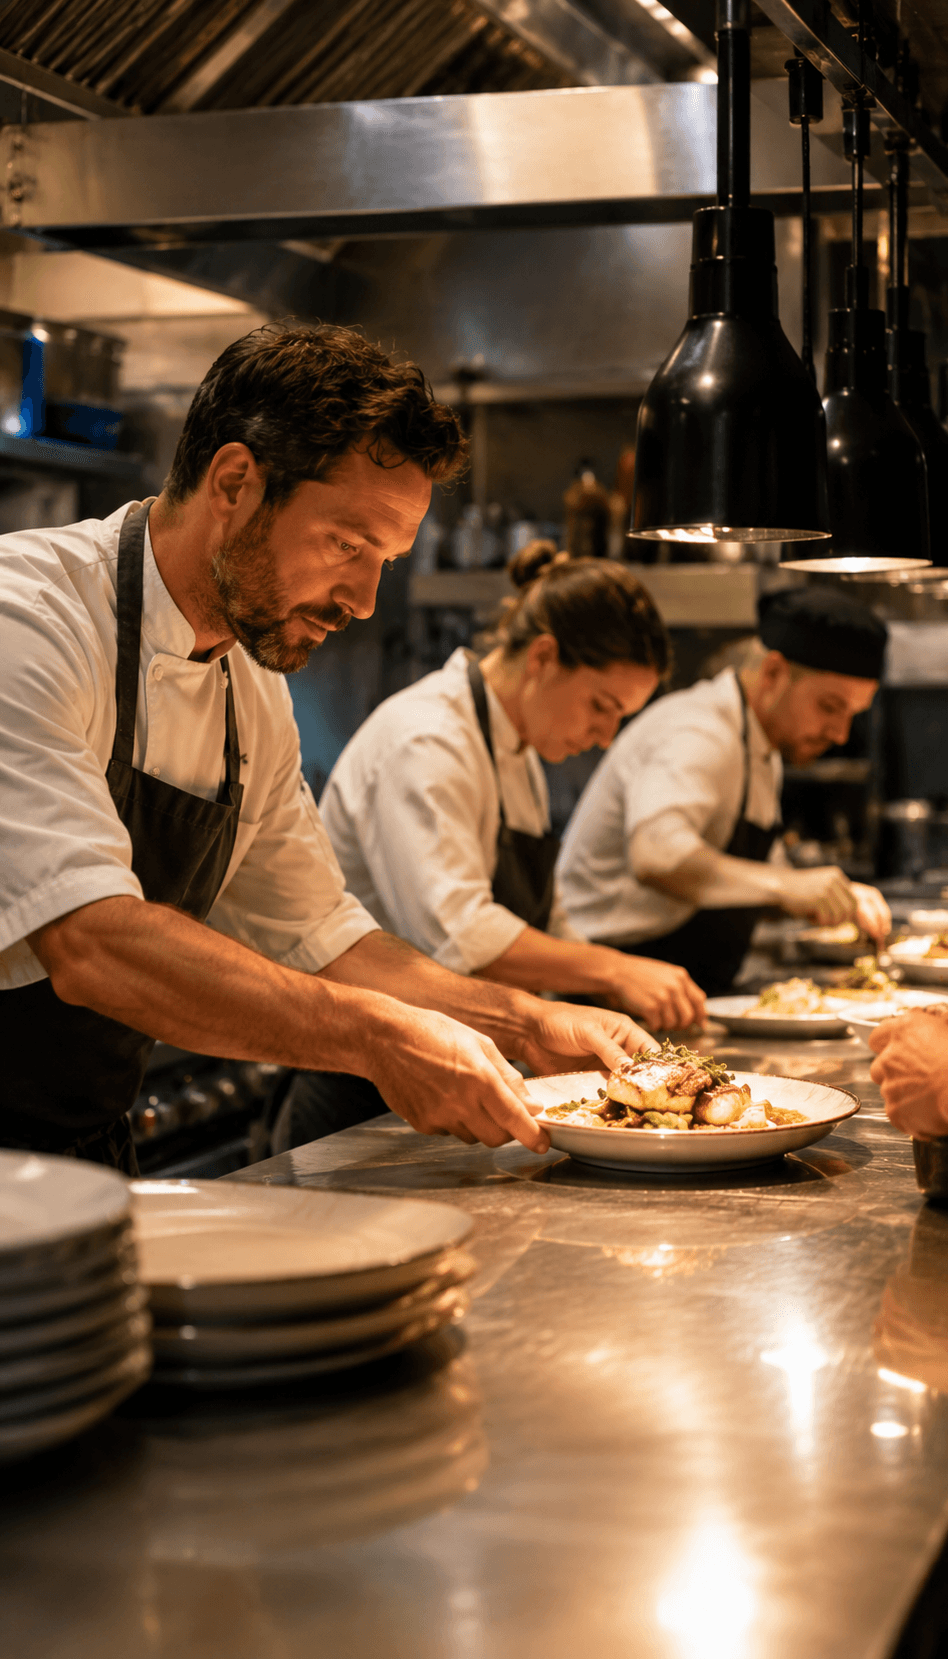
Chefs working in a commercial restaurant kitchen — restaurant insurance

Restaurant Insurance Brokers Australia

Restaurant Insurance Brokers Australia

Running a restaurant involves much more than serving good food.

Restaurants invest heavily in premises, commercial kitchen equipment, refrigeration, fit-outs, stock and staff.

Risks such as kitchen fires, equipment breakdowns, theft, burst pipes and liability claims can cause costly repairs and lost income.

Ideal Insurance Brokers helps restaurant owners across Australia arrange tailored Restaurant Insurance based on their business needs.

Speak With a Broker

Whether you run a restaurant, cafe, takeaway, fast-food outlet or bar, your insurance should reflect your actual risks.

Insurance Business 2025 Top BrokerageInsurance Business 2025 Fast Brokerage

Access across leading Australian insurers and underwriting agencies, including:

360 UnderwritingAG GuardAgile UnderwritingAIGAllianzATC InsuranceATLBerkley InsuranceBlue ZebraBrooklyn UnderwritingChubbClub MarineDUAL AustraliaGardGT InsuranceHMIAHollardIALInsuring AmbitionJUA UnderwritingMiramar UnderwritingMITTINTIPEN UnderwritingQBESURAVeroWoodina UnderwritingZurich
Chef plating dishes in an Australian restaurant kitchen — restaurant insurance australia

Tailored Protection

No Single Policy Fits All Restaurant Venues

No single restaurant insurance policy suits every business. The right cover depends on your premises, turnover, equipment, cooking methods, staffing and customer capacity.

A broker can assess your specific risk profile and arrange insurance tailored to how your restaurant operates.

Hospitality Insurance Australia

100+

Underwriters

98%

Claims Success Rate

15–25%

Premium Savings

4.9

Google Review Rating

Underwriting Variables

Key Factors That Define Your Restaurant Risk Profile

Insurance underwriters don't look at generic business labels. They evaluate concrete operational metrics. Reviewing these factors ensures your sums insured reflect true replacement values.

Dining Model

Fine dining, fast-casual, cafe, or licensed bar & restaurant.

Annual Turnover

Gross revenue defines your Business Interruption and liability tiers.

Location & Density

CBD dining hubs vs suburban high-turnover shopping strips.

Premises & Building

Construction type, building age, shared walls, and adjoining risks.

Lease Covenants

Tenant obligations for fit-out, plate glass, and landlord indemnities.

Cookline Appliances

Commercial fryers, ranges, char-grills, and exhaust canopies.

Cooking Methods

Accurate disclosure of charcoal, wood-fired ovens, and open flames.

Stock & Coolrooms

Peak holding values of fresh meat, seafood, dairy, and beverages.

Staffing Numbers

Kitchen hands, chefs, and front-of-house payroll allocations.

Takeaway & Delivery

Third-party courier integrations or in-house delivery vehicles.

Alcohol Licensing

Pouring alcohol, patron capacities, and late-night closing hours.

Claims History

Past slip-and-fall, spoilage, or fire incident track record.

Fit-Out Investment

Custom architectural joinery, dining furniture, and decor replacement.

BI Indemnity Period

Realistic months needed to rebuild and regain full trading revenue.

Unsure If Your Sums Insured Are Accurate?

Our brokers help Australian restaurant operators benchmark fit-out, stock, and equipment replacement values to eliminate co-insurance penalties.

What Does It Cover?

What Does Restaurant Insurance Cover?

  • Public & Products Liability

    Protects your restaurant against covered claims involving third-party bodily injury or property damage arising from business activities. Covers patron slip-and-falls, customer dining injuries, food-borne illness allegations, and third-party property incidents, subject to policy terms.

    Learn more
  • Business Interruption Insurance

    For many restaurants, Business Interruption is the most critical cover. If a covered fire, burst pipe, or storm forces you to close, this covers ongoing fixed expenses — commercial rent, staff wages, utilities, loan repayments, and supplier debts — while replacing lost gross profit.

    Learn more
  • Restaurant Property & Contents

    Protects dining furniture, interior fit-outs, bar fixtures, POS terminals, computer networks, and business contents against fire, storm, and insured disasters. We review your commercial lease to clarify tenant obligations versus landlord building insurance.

  • Commercial Kitchen Insurance

    The heart of your restaurant houses your most expensive assets: commercial ovens, deep fryers, char-grills, cooktops, dishwashers, and exhaust extraction hoods. Accurately declaring all equipment ensures claims for fire or breakdown are honoured without dispute.

    Learn more
  • Equipment Breakdown Insurance

    Protects against sudden mechanical or electrical failures involving coolroom compressors, refrigeration motors, combi-ovens, and commercial dishwashers. Covers repair or replacement costs and prevents extended trading shutdowns.

    Learn more
  • Restaurant Stock & Food Spoilage

    Restaurants hold substantial quantities of fresh meats, seafood, dairy, produce, and premium beverages. A refrigeration breakdown or power loss can spoil tens of thousands of dollars in stock. Cover is structured around peak holding values, not averages.

    Learn more
  • Restaurant Glass Insurance

    Covers shopfront windows, internal glass partitions, entry doors, sneeze guards, and display mirrors against accidental breakage. Leases frequently require the tenant to insure all perimeter plate glass.

  • Theft & Money Protection

    Provides protection against forced entry theft of equipment, alcohol inventory, and business cash held on the premises, in safes, or in transit to bank deposits, reflecting your venue's security measures.

  • Fire & Commercial Cooking Risks

    Kitchen fires represent the greatest physical catastrophe for food operators. Insurers require strict disclosure of deep fryers, charcoal pits, wood-fired pizza ovens, and extraction duct cleaning schedules to ensure full fire protection.

    Learn more
  • Liquor Liability, Takeaway & Delivery

    Specialist underwriting for licensed dining venues serving wine, beer, and spirits. Furthermore, we ensure food delivery operations — whether via direct staff drivers or third-party delivery apps — are appropriately protected.

Tailored by Dining Style

Restaurant Insurance for Different Types of Businesses

Real-World Claim Analysis

Restaurant Insurance Claim Scenario: Commercial Kitchen Fire

Weekend Evening ServiceFull dining room & peak table turns

The Event: Oil Flare-Up in Fryer Line Reaches Extraction Ducts

An established 7-day restaurant experiences an intense oil fire in the deep fryer line during dinner service. The blaze rapidly enters the exhaust canopy and ventilation ducts before fire suppression triggers. While structural building damage is contained, heat, toxic smoke, and soot force a mandatory 8-week closure for engineering repairs, deep duct cleaning, and council health certification.

The Revenue Threat: $0 Daily Takings, Yet Full Fixed Expenses Continue

Replacing a charred oven is straightforward. But while trading is halted, the venue earns zero income while continuing to owe $22,000/week in commercial rent, key staff retention wages, equipment finance, utilities, and vendor accounts.

How a Structured Restaurant Program Responds:

1. Property & Contents

Rebuilds the Physical Kitchen

Reimburses the full replacement cost of damaged fryers, ranges, exhaust canopies, electrical wiring, and dining room soot remediation.

✓ Full Equipment Replacement

2. Food Spoilage & Stock

Compensates Ruined Inventory

Pays for coolroom meats, seafood, dairy, and premium wine stocks ruined by smoke penetration or power disconnection during the shutdown.

✓ Re-Ordering Working Capital

3. Business Interruption

The Restaurant Balance Sheet Lifeline

Replaces lost gross operating profit and directly covers ongoing fixed expenses — keeping your lease paid, key staff on payroll, and debt serviced during repairs.

✓ Protects Against Involuntary Closure

Is Your Business Interruption Indemnity Period Long Enough?

Most restaurant rebuilding and council approvals take 6 to 12 months. Ensure your indemnity period keeps your cash flow secure throughout.

Risk Management

A Restaurant Insurance Review Could Identify Hidden Gaps

Insurance gaps may not become obvious until a claim occurs. Restaurants can be exposed through inadequate Business Interruption cover, underinsured commercial kitchen appliances, incorrect sums insured, or changes such as charcoal cooking that have not been disclosed to the insurer.

A comprehensive broker review can help identify and address these risks before they become costly problems.

Pricing Dynamics

How Much Does Restaurant Insurance Cost in Australia?

  • Restaurant Model & Seating

    A 40-seat licensed dining venue in Sydney CBD carries different liability and lease requirements than a suburban pizza shop or regional family diner.

  • Annual Turnover & Payroll

    Gross annual sales and staff wage rolls directly determine required Business Interruption sums insured and public liability exposure tiers.

  • Cooking Equipment & Ducts

    Use of open flames, gas ranges, charcoal grills, wood-fired ovens, and deep fryers requires higher fire underwriting than cold-prep operations.

  • Alcohol Licensing & Trading Hours

    Pouring alcohol and operating late into the evening introduces additional patron liability and security risk factors.

Why Ideal Insurance Brokers

Why Use an Insurance Broker for Restaurant Insurance?

Insurance broker discussing restaurant insurance options with venue owners
  1. 01

    Cover for Real Risks

    We build restaurant insurance around your actual trading risks, not simply the cheapest quote.

  2. 02

    Access to 100+ Underwriters

    We compare leading Australian insurers and specialist hospitality markets for competitive, suitable cover.

  3. 03

    Lease & Contract Review

    We check lease obligations, glass cover and public liability requirements to help ensure your policy meets your contractual needs.

  4. 04

    Claims Advocacy

    We work with the insurer and loss adjusters during a claim, helping you focus on running your restaurant.

Speak With a Broker

Frequently Asked Questions

The insurance requirements depend on the restaurant's operations. Common core areas include Public & Products Liability, Restaurant Property & Contents, Commercial Kitchen Equipment, Equipment Breakdown, Food Spoilage, and Business Interruption. View restaurant cover options

It can be extremely important because a restaurant continues to incur significant fixed expenses — commercial rent, staff wages, utilities, loan repayments, and supplier accounts — while completely unable to trade following a covered event. Learn about Business Interruption

Depending on the policy, commercial kitchen equipment can be insured against covered damage like fire, storm, and water leaks. Mechanical or electrical breakdown of motors, compressors, and appliances requires Equipment Breakdown cover. Kitchen equipment details

Food spoilage can be covered in certain circumstances, depending on the cause of loss (such as coolroom compressor breakdown or power disconnection) and policy wording. Restaurants should base sums insured on peak inventory holdings. Food spoilage cover

Fire damage is typically covered where the policy provides fire protection and the loss falls within policy terms. It is essential that restaurants accurately disclose all cooking methods, deep fryers, and duct cleaning maintenance. Commercial fire risks

The appropriate limit depends on the restaurant's turnover, seating capacity, lease covenants, and contractual obligations. Most Australian landlords and shopping centre operators require a minimum of $10 million or $20 million Public Liability. Public liability overview

Yes. Turnover, kitchen appliances, menu styles, staff numbers, cooking methods, premises, and stock values evolve over time. An annual policy renewal is an essential opportunity to verify that your insurance still matches how you trade.

Yes. An insurance broker assesses your venue's unique risks, obtains competitive terms across 100+ underwriters, explains critical policy differences, and acts as your direct claims advocate when an incident occurs.

Get a Restaurant Insurance Review

Your restaurant depends on its equipment, staff, customers and revenue. Speak with Ideal Insurance Brokers about Restaurant Insurance Australia and protect your business.

Speak With a Broker
Speak With a Broker